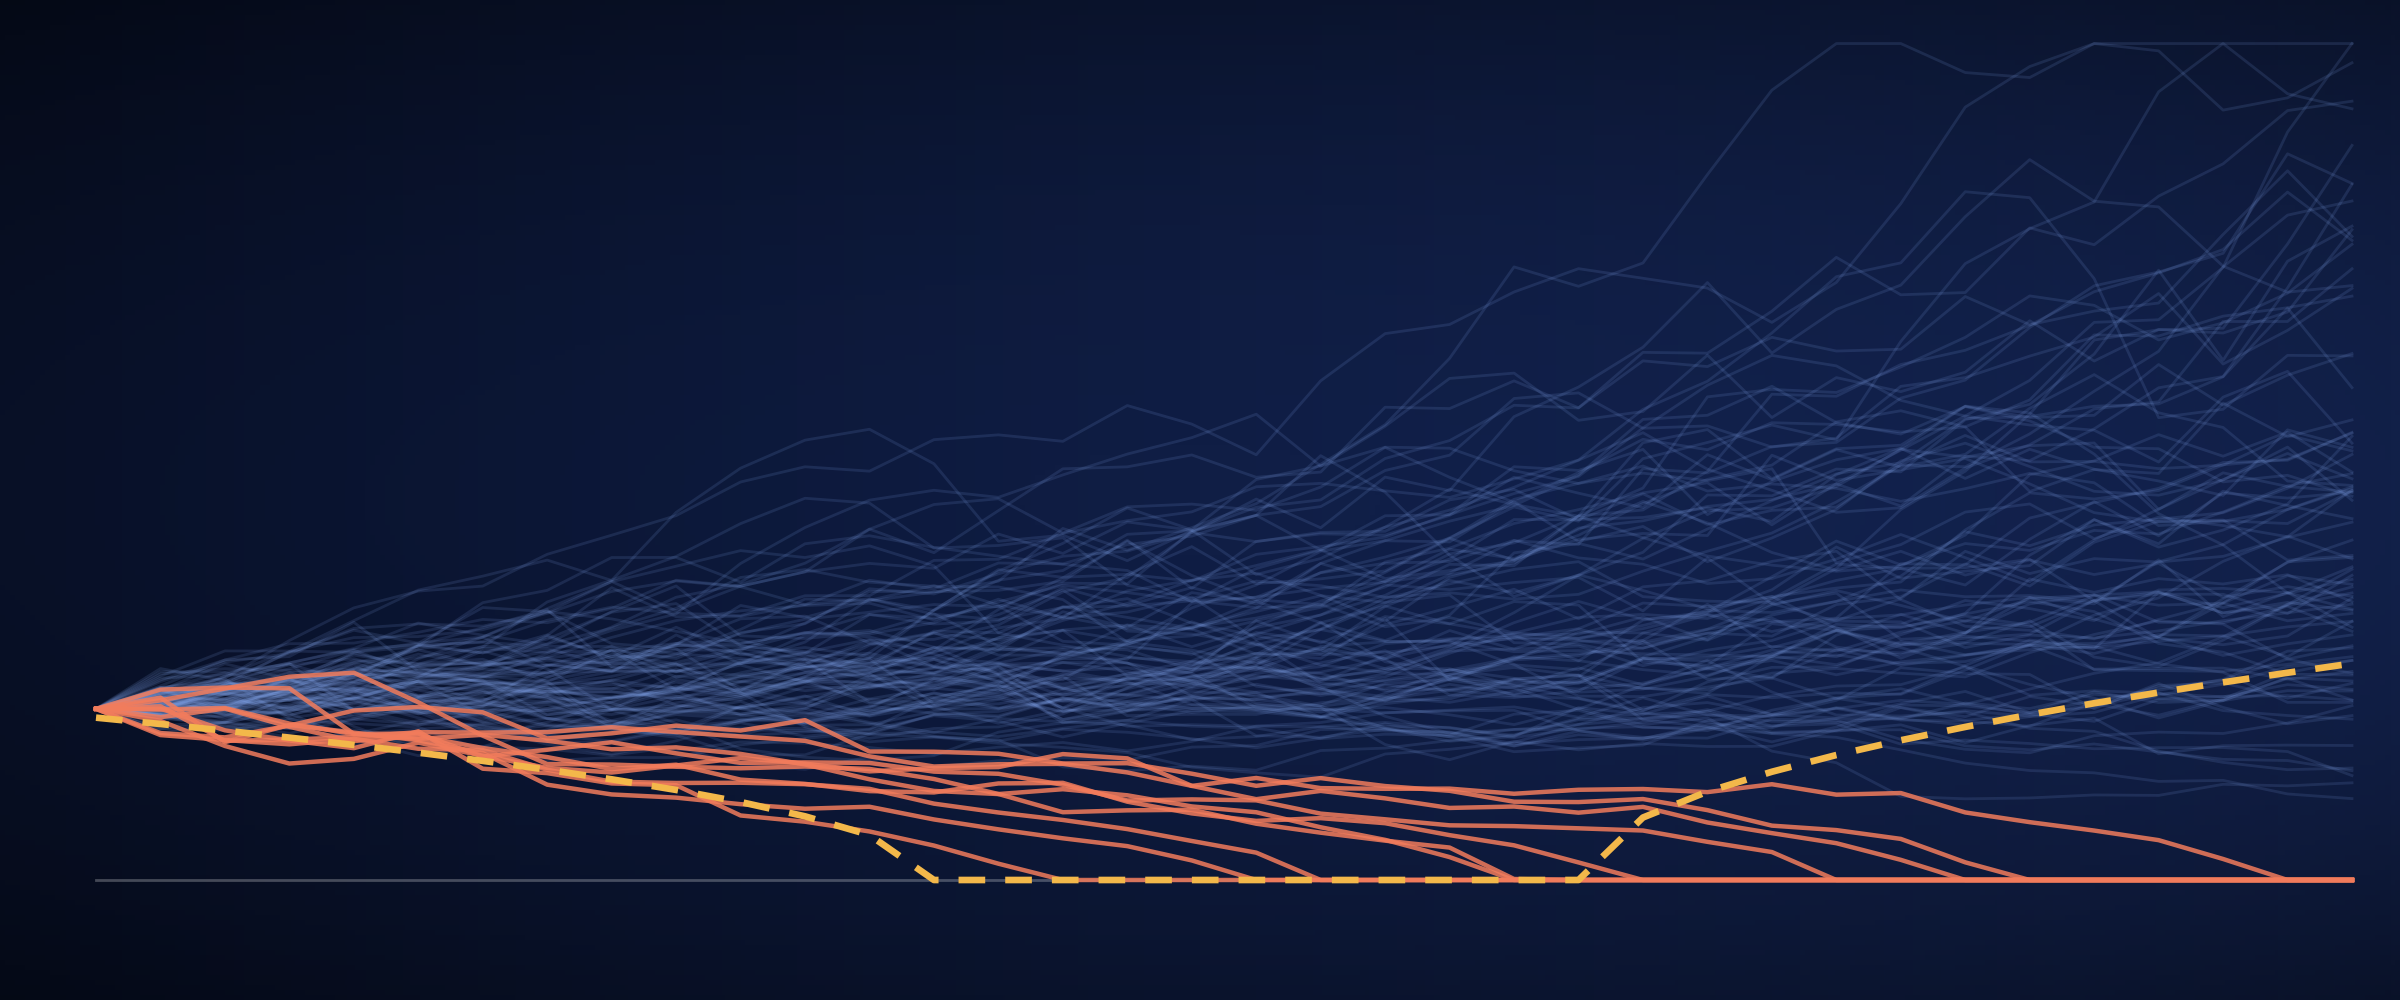
A few years ago, while planning my own early retirement, I put my numbers into a popular planning tool. The chart showed my net worth hitting zero, staying there for a while, and recovering about twenty years later. The headline number said I had a 90% chance of success.
I couldn't make those two things agree, so I went digging into how these percentages are calculated. What I found applies to most planners, not just the one I was using.
A success rate looks like a simple answer to the biggest question in retirement: will my money last? In reality, it's the result of several choices about what counts as success, where future returns come from, and how you'll behave along the way. Those choices are often buried, and they can move the number a lot.
Here are the five that matter most.
1. "Success" isn't defined the same way everywhere
Some tools count a plan as a success if the balance is at or above $0 at the end, even if it ran dry along the way and recovered later from a home sale, an inheritance, or a late income stream. Others require spending to be covered in every single year.
The same plan can score very differently under those two definitions. That's very likely what happened to me: a plan with years of empty accounts could still pass if the balance recovered by the end.
2. How does the planner handle a shortfall?
Planners also differ on what happens after the savings run out. Some keep the plan going by modeling the shortfall as debt, as if you could borrow whatever you need. But someone in their 90s with no savings left may not qualify for that loan, at least not on good terms.
Net worth can hide this too. A chart can show millions of dollars of net worth while your savings sit at zero, because most of what's left is the house you live in. Home equity can help, but only if you're willing to sell the house or borrow against it.
Some planners can model selling assets like real estate to cover a shortfall. To be accurate, they need to account for the commissions and taxes on those sales.
So it's worth asking what your planner actually counts. Does selling your house count as recovering? And if the plan borrows to fill a gap, does that count as a failure?
3. Where the returns come from matters
A planner has to assume something about future markets, and most use one of two methods.
| Historical simulation | Monte Carlo | |
|---|---|---|
| How it works | Replays your plan through actual market history | Draws random returns from an assumed average and spread |
| Strength | Includes real events like the Depression, 1970s inflation, and 2008 | Can run thousands of paths |
| Weakness | Only about a century of data, with heavily overlapping start years | Only as good as its assumptions |
Both have limits that are easy to miss.
History is realistic, but there's less of it than it seems. Because the starting years overlap, a 30-year retirement has only a handful of truly independent periods to learn from.
Monte Carlo seems to solve that problem with volume, but more paths only reduce random noise. They don't make the assumptions any more correct. If the assumed average return is a point too high, 10,000 paths will confidently give you the wrong answer.
4. A few inputs move the number more than anything else
If you only have time to check a few assumptions, start with these:
- The assumed return, and whether it's after inflation. A 7% return with 3% inflation is about 4% in real terms, and that gap adds up over a 30-year retirement.
- Fees. A plan that ignores a 1% annual fee is effectively assuming a return one point too high.
- Taxes. Paychecks, Social Security, investment gains, and traditional 401(k) and IRA withdrawals can all be taxed. A plan that ignores taxes treats that money as spendable when it isn't, so its success rate is too high.
5. The number assumes you never change anything
Most success rates assume you keep spending the same inflation-adjusted amount no matter what the market does. Real people don't behave that way. They cut back in a bad year, delay a big purchase, or pick up some work.
That's why an 80% plan with room to cut spending can be safer than a 95% plan with none. A useful way to think about it: the success rate is closer to the odds that you won't need to adjust than the odds that you'll be okay.
If you're waiting for your planner to tell you there's a 100% chance of success before you retire, you might be waiting indefinitely.
Some questions to ask any planner
Before you trust a success rate, find out:
- How does it define success: ending balance, or every year covered?
- When savings run out, does it assume you can sell property or borrow?
- Are returns historical or randomly generated, and what average does it assume?
- Are the figures adjusted for inflation?
- Does it model taxes on all your income, including withdrawals?
- Does it assume your spending never changes?
How to use the number
A success rate is still useful. It's a quick way to compare one version of your plan with another, as long as both are measured the same way. It just isn't the final verdict on your retirement, and it isn't a prediction.
That chart showing my net worth at zero is what started Fikata. I wanted a planner I could check, so its methodology is public. A path only counts as a success if your income and accounts cover your expenses, debt payments, and taxes in every year of the plan. Property you've marked as available to sell can be sold to get there, but Fikata never automatically borrows money to cover a shortfall. Your plan is replayed through US market history since 1920, with the inflation that came with it, and taxes are calculated every year on every path.
That means Fikata has the limits of any historical simulation, so its answer is a test against the past, not a forecast. It doesn't model flexible spending yet, so read its success rate the way I described in point 5: closer to the odds that you won't need to adjust. But you can see exactly what's being tested, and that's the right place to start with any success rate.
Erik Bielefeldt
Founder, Fikata
Fikata provides educational information, not financial, tax, or legal advice. Examples and figures are illustrations, and your situation may differ. See our Terms of Service.
Join the free beta
Open a sample plan and start exploring, no signup required. Already have an account? Sign in and pick up where you left off.